$3,850
5201 Kinnabeck Lane, Columbus, OH 43220(380) 205-0733Rent Savings
- 4 units available
- 4 bed
- Amenities
In unit laundry, Patio / balcony, Pet friendly, 24hr maintenance, Garage, Stainless steel + more
Verified listing
Verified
Renters insurance can help pay to replace your belongings after a covered loss, protect you from certain liability claims, and cover additional living expenses if a covered event temporarily makes your rental unlivable. Your lease may also require you to carry a policy.
Choosing a policy isn't just about price. Before buying, check your lease requirements, estimate what your belongings are worth, compare deductibles and coverage limits, and look closely at exclusions.
Renters insurance is insurance designed for people who rent an apartment, house, condo, or other home. It can protect your personal property and provide liability coverage if something goes wrong.
Unlike homeowners insurance, renters insurance generally isn't designed to insure the building itself. Your policy focuses primarily on you, your belongings, and certain financial risks you face as a renter.
According to the National Association of Insurance Commissioners (NAIC), renters insurance can cover personal belongings and provide liability protection. Some policies also provide coverage for additional living expenses after a covered loss.
Say a fire damages your apartment and destroys your couch, clothes, and laptop. Personal property coverage may help reimburse you for those belongings, subject to your policy's limits, deductible, and other terms.
If that same covered fire makes your apartment temporarily uninhabitable, additional living expense coverage may help pay certain costs above your normal living expenses while you're displaced.
The key word is covered. Insurance pays according to the policy, including its limits, exclusions, and conditions.
If replacing your belongings after a major loss would put a serious dent in your savings, renters insurance can provide useful protection.
Even a small apartment can hold a surprising amount of stuff. Think beyond your laptop and TV. Your clothes, furniture, kitchenware, books, shoes, bedding, electronics, and everyday items can add up quickly.
Renters insurance can also provide protection beyond your belongings. Personal liability coverage may help if you're legally responsible for certain injuries or property damage, while additional living expense coverage may help after a covered loss makes your home temporarily unlivable.
Your first question, however, should be simpler: Does your lease require it?
Your landlord may require renters insurance through your lease, subject to applicable laws and housing-program rules. Check the coverage amount, effective date, and proof-of-insurance requirements. Our guide to renters insurance requirements explains what to check and which exceptions may apply.
Renters insurance commonly combines several types of protection, including personal property, personal liability, medical payments to others, and additional living expenses.
Exactly what's covered depends on your policy, the cause of the loss, your coverage limits, your deductible, and any exclusions.
Here's the basic breakdown:
| Coverage | What it can do |
|---|---|
| Personal property | Helps repair or replace your belongings after certain covered losses, such as theft or fire |
| Personal liability | May help with covered costs if you're legally responsible for injuring someone or damaging their property |
| Medical payments to others | May cover certain medical expenses when a guest is injured, subject to policy terms |
| Additional living expenses or loss of use | May help pay certain extra costs if a covered loss makes your rental temporarily uninhabitable |
In plain English, personal property coverage is for your stuff. Liability coverage addresses certain claims against you. Additional living expense coverage may help when a covered loss means you temporarily can't live at home.
For exclusions, coverage limits, and worked claim examples, see our guide to what renters insurance covers.
Renters insurance doesn't cover every type of damage, every belonging, or every person living in your apartment.
Common gaps and exclusions can include:
The exact exclusions depend on your policy.
Standard renters insurance generally does not cover flooding caused by events such as heavy rainfall, storm surge, or overflowing bodies of water. The National Flood Insurance Program (NFIP) offers contents coverage for renters that can protect belongings against covered flood damage.
Don't confuse external flooding with every kind of water damage. A renters policy may cover certain sudden water losses, depending on the cause and policy terms.
Standard renters insurance commonly excludes earthquake damage.
Depending on where you live and your insurer, separate earthquake coverage may be available. If earthquakes are a meaningful risk where you live, check your options before assuming your standard policy covers them.
Renters insurance does not replace auto insurance. Damage to or theft of your vehicle generally falls under auto coverage.
However, personal belongings stolen from a vehicle may be covered under your renters insurance personal property coverage, depending on the policy and circumstances. Your car and the stuff inside your car are two different insurance questions.
Your overall personal property limit isn't the only number that matters.
Certain categories of property, such as jewelry, art, collectibles, or other high-value belongings, may have special limits. The NAIC recommends checking whether unusually expensive items require additional coverage, sometimes called a rider or floater.
If you own something expensive, don't assume its full value is covered just because your total personal property limit is high enough.
An unrelated roommate isn't automatically covered simply because you share an address. Whether roommates can share renters insurance depends on the insurer and applicable state rules. Some insurers allow an unrelated roommate to be added to a policy, while others require separate policies.
Ask the insurer who qualifies as an insured person before assuming anyone else's belongings or liability are protected.
Standard renters insurance generally does not cover damage caused by pests such as rodents, insects, or bedbugs.
Policies often treat infestations as a maintenance issue rather than a sudden covered event. Your lease may separately explain who is responsible for prevention, treatment, or related costs.
Renters insurance isn't designed to pay for belongings that wear out through ordinary use.
A laptop that fails after years of use is different from a laptop damaged in a covered fire. Insurance generally responds to covered events, not ordinary deterioration.
Renters insurance works by covering specified losses up to the limits and according to the terms of your policy.
You pay a premium to maintain coverage. If something happens that you believe is covered, you contact your insurer and file a claim.
The insurer reviews what happened, whether the loss qualifies for coverage, which coverage applies, and how much the policy may pay.
For a personal property claim, your deductible may reduce the amount the insurer pays. For example, suppose you have a $500 deductible and experience a covered personal property loss. You generally bear the deductible portion before insurance pays the eligible amount above it, subject to your policy's limits and terms.
Two other terms matter when you're comparing personal property coverage: actual cash value and replacement cost.

Replacement cost and actual cash value can result in very different payouts after a covered loss.
According to the National Association of Insurance Commissioners' guidance on actual cash value and replacement cost, actual cash value accounts for depreciation, while replacement cost generally pays to repair or replace covered property with materials of like kind and quality, subject to the policy's terms and limits.
Imagine a covered loss destroys a couch you've owned for several years.
With actual cash value coverage, depreciation may reduce the amount you receive. With replacement cost coverage, the insurer may reimburse the cost of a comparable replacement according to the policy.
Replacement cost coverage may cost more, but it can reduce the amount you have to contribute when replacing older belongings.
The cost of renters insurance depends on factors such as your location, coverage limits, deductible, and insurer.
As of September 2026, NerdWallet's national renters insurance rate analysis found an average renters insurance cost of $165 per year, or about $14 per month.
That benchmark assumes a renter with:
Treat that figure as a budgeting benchmark, not a quote. Your own rate can vary based on your location, coverage choices, insurer, and other rating factors.
When comparing quotes, make sure you're comparing similar policies. A cheaper premium isn't necessarily a better deal if it comes with substantially lower limits, a larger deductible, or coverage that doesn't fit your needs.
There's no single coverage amount that's right for every renter.
Start with your belongings. Estimate what it would cost to replace everything you would want covered after a major loss, rather than guessing based on the handful of expensive items that come to mind first.
A home inventory can help.
Go room by room and record:
For expensive items, keep receipts, serial numbers, photos, appraisals, or other records when possible. Store your inventory somewhere you could still access if your phone or computer were lost or damaged.
Then consider liability coverage separately. Think about the financial protection you want if you're responsible for a covered injury or property-damage claim.
Finally, look at the deductible. Your coverage isn't especially useful if you've chosen a deductible you'd struggle to pay when you need to file a claim.
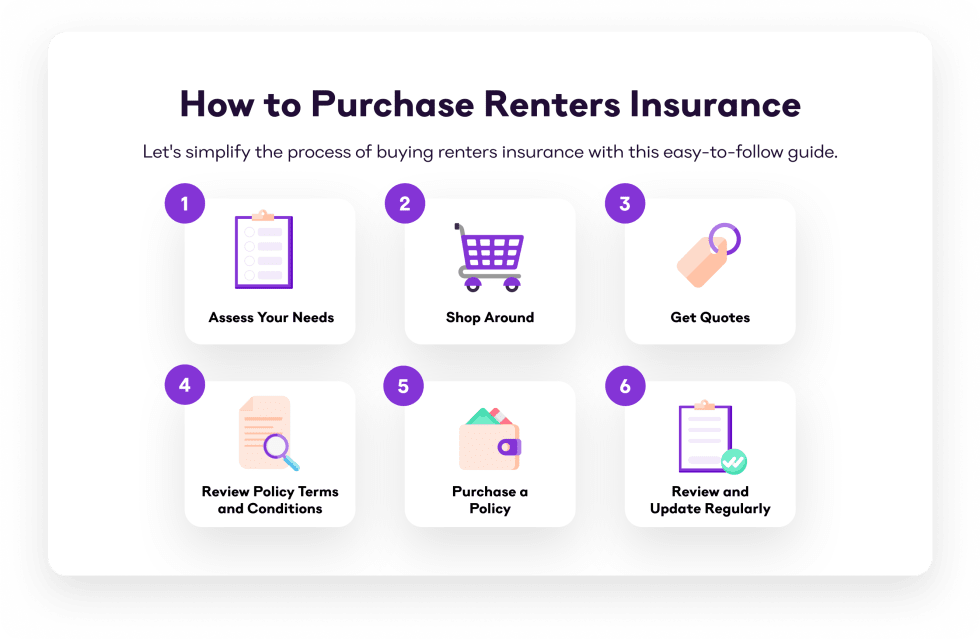
Once you know what coverage you need, shopping for renters insurance becomes much easier. Follow these steps to compare policies and make sure you have the coverage your lease and belongings require.
Start with your lease. If renters insurance is required, find out:
Knowing these requirements before you request quotes helps you compare policies that meet your lease terms.
Create a home inventory and estimate what it would cost to replace your belongings. Pay particular attention to expensive items and categories that may have special policy limits.
Use that estimate to choose an appropriate personal property coverage limit. You’ll also need to choose a liability limit and deductible. Your liability limit should meet any minimum required by your lease and provide the amount of protection you want.
A deductible is the amount you're responsible for under applicable coverage before the insurer pays the eligible remainder of a covered claim. A higher deductible may lower your premium, but make sure you could comfortably afford it if you needed to file a claim.
Before requesting quotes, have your:
Insurers may also ask questions about the property, its safety features, and other details that could affect your quote.
Get quotes from more than one insurer when possible, using the same or similar coverage limits and deductible for each. Otherwise, a lower premium may simply reflect less coverage or different policy terms.
Compare: Personal property limits
The premium tells you what you pay. The policy tells you what you get. If something isn't clear, ask the insurer or agent before purchasing.
The date you purchase insurance isn't always the same thing as the date coverage begins. Confirm the effective date on your policy documents and make sure it meets your lease requirements.
If you're replacing an existing policy, coordinate the dates so the new coverage begins before or when the old policy ends.
Once you've confirmed the policy meets your needs, purchase the coverage. If your landlord or property manager requires proof of insurance, follow their instructions for submitting it.
Keep your policy documents and proof of insurance somewhere easy to access. You may also want to save your home inventory, photos, receipts, and other records somewhere separate from your primary devices.
Review your coverage when you:
Confirm that your address, coverage limits, deductible, and insured people are still accurate.
To file a renters insurance claim, contact your insurer as soon as possible and follow its instructions for documenting the loss.
The process may include:
Don't throw away damaged property until the insurer says you can, unless keeping it would be unsafe.
Your policy explains the required steps and deadlines. Follow those terms, even when the situation is stressful.
Renters insurance is one of those moving tasks that's easy to leave until the last minute.
Read the exclusions before buying and confirm the effective date. Then save your policy documents and home inventory somewhere secure.
Once that's handled, you can get back to the more exciting part: finding a place that feels like home.
Before buying, confirm that the policy meets your lease requirements and covers what you need. Save your policy documents and home inventory somewhere accessible.
Renters insurance is a policy that protects a renter's personal belongings, provides certain personal liability coverage, and may pay additional living expenses when a covered loss makes the rental temporarily uninhabitable. It generally does not insure the building itself.
Renters insurance may be required by your lease where applicable law permits, but it is not universally required nationwide. Even when it is optional, a policy can protect your belongings and provide certain liability and additional living expense coverage.
A landlord's insurance generally covers the rental building, not a tenant's personal belongings. You need your own renters insurance policy if you want eligible belongings protected against covered losses.
Renters insurance commonly includes personal property coverage, personal liability coverage, medical payments to others, and additional living expenses after certain covered losses. Limits, deductibles, covered events, and exclusions vary by policy.
NerdWallet's September 2026 rate analysis found a national average of $165 per year, or about $14 per month. That estimate assumes a renter with $30,000 in personal property coverage, $100,000 in liability coverage, and a $500 deductible. Your rate may differ.
Choose personal property coverage based on what it would cost to replace the belongings you want insured, then consider your liability needs separately. Check your lease for required minimums and review special limits for valuable items.
An unrelated roommate isn't automatically covered by your renters insurance policy. Some insurers allow roommates to share a policy or be added as an insured person, while others require separate policies.
Standard renters insurance generally does not cover external flooding, such as flooding caused by heavy rainfall, storm surge, or overflowing waterways. Renters can purchase separate flood coverage, including contents coverage available through the National Flood Insurance Program.
Standard renters insurance commonly excludes earthquake damage. Separate earthquake coverage may be available depending on your location and insurer.
Renters insurance may cover personal belongings stolen from a car if the loss meets the policy's terms. Theft of or damage to the vehicle itself generally falls under auto insurance.
Renters insurance may provide liability coverage for certain injuries or property damage caused by a pet, but exclusions and restrictions can apply. It generally does not cover veterinary care for your pet. If you have a pet, check the policy's liability terms and exclusions. Our guide to renters insurance and pets explains what to look for.
Renters insurance commonly includes additional living expense or loss-of-use coverage when a covered loss makes the rental temporarily uninhabitable. Eligible expenses, limits, duration, and conditions depend on the policy.
Replacement cost coverage generally pays based on the cost of repairing or replacing covered property without a deduction for depreciation. Actual cash value accounts for depreciation, which can result in a lower payout for older belongings.
A renters insurance deductible is the amount you're responsible for under the applicable coverage before the insurer pays the eligible remainder of a covered claim. A higher deductible may lower the premium but can increase what you pay after a loss.
To file a renters insurance claim, contact your insurer promptly and document the loss with photos, videos, receipts, and an inventory when possible. Submit any police, fire, or other reports required by the insurer and keep receipts for potentially eligible additional living expenses.
Renters insurance should be effective by the date required in your lease or whenever you want coverage to begin. If your landlord requires insurance before move-in, confirm the effective date and submit proof as instructed.
You may be able to update or transfer renters insurance instead of canceling it when you move. Ask your insurer whether your policy can be updated for the new address. If you need to end it, follow our renters insurance cancellation guide.
Yes. According to the Insurance Information Institute, Renters insurance generally covers bicycles under personal property coverage if they’re stolen in a covered loss. Your insurer will typically subtract your deductible from the claim, and coverage is subject to your policy’s limits.
Coverage may also apply if your bike is stolen away from home, although off-premises coverage can have separate limits. If you own an expensive bike, check your policy for special limits or ask your insurer about additional coverage.
Renters insurance can protect more than your stuff. A good policy may provide personal property coverage, liability protection, and additional living expense coverage after certain covered losses.
Before buying, start with your lease. Then estimate the value of your belongings, choose a deductible you could realistically afford, compare liability limits, review exclusions and special limits, and confirm your effective date.
The cheapest policy isn't necessarily the one that gives you the protection you need. Compare what you're actually getting for the premium.
Ready to start your search? Take the Apartment List quiz to get matched with apartments that fit your needs.
In unit laundry, Patio / balcony, Pet friendly, 24hr maintenance, Garage, Stainless steel + more
In unit laundry, Patio / balcony, Pet friendly, Stainless steel, Walk in closets, Gym + more